If you are running an Estonian OÜ as an e-resident, submitting your annual accounts is not a formality that can be ignored or postponed indefinitely. Every Estonian company must file an annual report, regardless of turnover, profit, or even business activity. In 2026, this obligation remains unchanged, but the expectations around accuracy, documentation, and digital submission are stricter than many founders realise.
This guide explains what Estonian annual accounts are, what must be submitted in 2026, and how e-resident founders can prepare without last-minute pressure or unnecessary risk. All examples and requirements below apply to annual reports submitted in 2026 for the previous financial year.
Annual accounts (in Estonian aastaaruanne) are mandatory financial statements submitted once per year to the Estonian Business Register. They summarise your company’s financial position and activity during the financial year and are publicly accessible.
This transparency is a core principle of Estonia’s business environment. Anyone, business partners, banks, investors, or authorities, can view your company’s annual report online. For e-resident founders, this often becomes the first external “credibility check” of the company.
Importantly, annual accounts must be submitted even if the company had no activity. A company with zero turnover, no invoices, and no employees is still required to file a report. Failing to do so can trigger fines and, eventually, deletion from the register.
Annual report obligation in Estonia (legal framework)
Under the Estonian Commercial Code and Accounting Act, every registered OÜ must submit annual accounts within six months after the end of the financial year.
For companies using the calendar year:
Deadline for submissions:Calendar-year companies: 30 June of the following year (for financial year 2026, 30 June 2027)
Responsibility lies with the management board, not the accountant. Even if accounting is outsourced, board members remain legally accountable for late or incorrect filings.
Penalties for non-compliance may include:
Warning notices from the register
Fines (typically starting from a few hundred euros)
Court-initiated deletion of the company
Personal liability for board members in prolonged cases
Submitting the annual report promptly has benefits beyond compliance. For example, dividends can only be distributed after the accounts are submitted, so handling this early makes financial planning smoother.
Does an inactive (dormant) company still need annual accounts?
Yes. This is one of the most misunderstood aspects among e-residents.
An Estonian company that had no business activity during the year must still submit annual accounts. In such cases, the report may be simplified, but it must still be filed correctly and on time.
Crucially, “no activity” has a specific accounting meaning. Even a single transaction — for example:
Bank fees
Card payments
Subscription charges
Capital injections
Loan repayments
means the company is not dormant under Estonian rules.
Misclassifying a company as dormant is one of the most common reasons reports need correction later.
What is included in Estonian annual accounts?
The exact structure depends on company size and activity, but for most e-resident OÜs, the annual report includes the following core elements.
Micro and small companies: can submit simplified reports.
Medium and large companies: must submit complete reports, with additional financial statements and notes.
Management report
The management report describes the company’s activities and development during the year. Micro-companies are not legally required to submit one, but in practice it is often advisable to include at least a brief statement, especially if the report will be reviewed by third parties.
Even a short explanation of what the company does (or did not do) during the year can add clarity and credibility.
Balance sheet (statement of financial position)
The balance sheet shows what the company owns (assets), owes (liabilities), and the remaining equity at year-end.
Typical items include:
Bank balances
Receivables
Share capital
Retained earnings
Loans and unpaid invoices
Equity must not fall below statutory thresholds without corrective action. Persistent negative equity can trigger legal obligations for the management board.
Profit and loss statement (income statement)
The profit and loss statement summarises:
Revenue
Expenses
Operating profit or loss
Financial income and expenses
Estonia does not tax retained annual profits, but this statement is still essential for transparency and future dividend decisions.
Notes to the financial statements
Notes explain how figures were calculated and disclose mandatory information, such as:
Accounting policies
Related-party transactions
Labour costs (if applicable)
Loans to or from shareholders
These notes are often underestimated but are closely reviewed by accountants and authorities.
Additional statements (where applicable)
Depending on company size or audit requirements, reports may also include:
Cash flow statement
Auditor’s report
A cash flow statement is not mandatory for micro and small companies. It gives an overview of how cash flows in and out of the business, covering operating, investing, and financing activities. Larger companies, or those subject to a mandatory audit, must also include an auditor’s report to verify the accuracy of the financial statements.
Most micro- and small e-resident companies are exempt from audits, but thresholds should be reviewed annually.
Worked example: a simple profit and loss statement and balance sheet
Proper preparation of your annual accounts starts with gathering and organizing all relevant financial data. Here’s how the two core financial statements are prepared, using examples to explain specific elements and calculations. Please note that all figures are always reported in euros. If you hold or trade in other currencies, you need to convert to euros using the exchange rate of the balance date. Original accounts must be submitted in Estonian, but you can produce English-language copies by selecting them in the e-Business Register.
Profit and loss statement (income statement)
This statement summarizes your company’s revenue and expenses. Key elements are Revenue, Cost of Goods Sold, Labor cost, etc.
Operating profit would be calculated as Revenue minus all operating expenses, resulting in an Operating Profit.
Adding interest income/cost and other financing-related items gives the Profit Before Tax, which can be much higher if you earn interest or have capital gains, or vice versa.
In this sample profit and loss statement, we have a company that recorded (but maybe has not yet received) a sales invoice of 2500 euros but also recorded its first expense. Operating profit would be 2500 euros minus the first expense recorded, which was probably already paid by the company card. So, the total profit before tax would be €2500-199=€2301. Estonia has no annual corporate tax, so the annual profit is unaffected by tax.
Profit and loss statement (income statement)
This statement shows what the company owns (assets) and owes (liabilities), and the equity held by shareholders. Key elements are Current Assets and Non-Current Assets, which sum up as Total Assets. Equity includes issued share capital and retained earnings and should equal your total assets minus liabilities. Liabilities can be shareholder loans, credit card debts, or unpaid invoices from your suppliers.
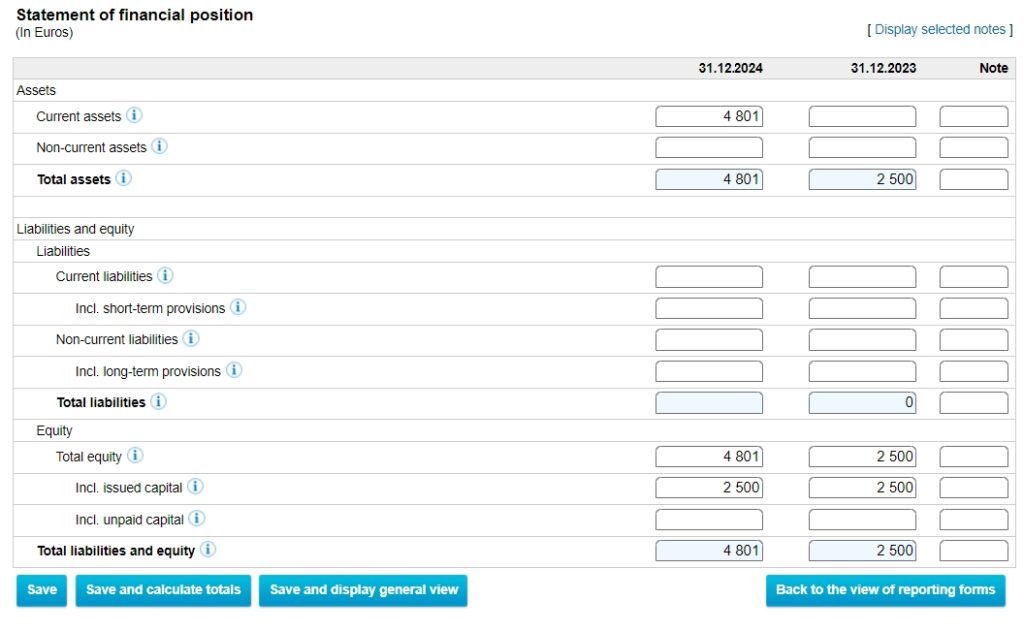
In this sample balance sheet, we have a company that paid up share capital of 2500 euros, recorded (but maybe did not yet receive) a sales invoice of 2500 euros, and recorded their first expense as 199 euros.
Current and total assets would be 2500 euros of cash paid to the company bank account by the shareholder for the shares, plus 2500 euros that the company’s first client must pay, minus 199 euros for the first expense recorded and probably already paid by the company card.
So, the operating profit that equals retained earnings in this sample (2500-199=€2301) will make the total equity with zero liabilities: 2500+2301=€4801. Equity is simply the net value of the company for its shareholders.
Sample balance sheet of a new Estonian company
A balance sheet helps to assess your company’s financial health. The management board is responsible for keeping the company solvent. The annual accounts balance sheet is how the public knows if the company is becoming insolvent. Reporting that the company has equity below half of the registered share capital triggers the court’s demand to improve the company’s solvency by injecting more capital, etc.
Bank statements and source documents: what is required?
For annual accounts, bank statements remain mandatory for all companies that have a bank account, even if there were no transactions.
Statements must:
Cover the full financial year
Include all company accounts
Match recorded transactions
In Estonia, bank statements alone are not sufficient. Every expense must be supported by a source document (invoice, receipt, or equivalent). Missing documentation can delay submission or result in incorrect reporting.
This is one reason many founders struggle if preparation starts too late. The Estonian Accounting Act requires you to keep all accounting documents for seven years after the end of the financial year, and every expense must be linked to a source document.
Why annual accounts often become stressful for e-residents
The deadline itself is predictable. The problems usually arise from timing.
In spring, accountants handle a high volume of reports. Response times slow, corrections take longer, and small issues turn into delays. For e-residents, additional risks include:
Expired digital ID cards
Missing access to e-services
Delays in retrieving bank data from foreign banks or fintech providers
Companies that prepare early typically submit calmly and on time. Those that wait often face avoidable back-and-forth.
Outsourcing annual accounts vs. submitting yourself
Some founders submit annual accounts independently through the Business Register. This can work for very simple cases, especially truly dormant companies. Be aware that even minor errors can lead to an offence for submitting false data, so proceed cautiously.
However, common risks include:
Misclassification of activity
Incorrect equity calculations
Missing disclosures
Technical submission errors
Outsourcing to an Estonian accounting provider reduces these risks, particularly for active companies or founders unfamiliar with Estonian accounting logic.
Annual accounts for Estonian companies with Unicount
Unicount prepares annual accounts for both active and dormant Estonian OÜs, including companies owned by e-residents managing everything remotely.
Our approach focuses on:
Early clarification of company status
Review of bank statements and documentation
Annual report preparation by an expert accountants
Correct classification under Estonian rules
Online submission to the Business Register
This allows founders to treat annual reporting as a routine compliance task, not a seasonal emergency.
Final thoughts
Annual accounts are not optional, negotiable, or something that can be “fixed later”. In Estonia, transparency and accuracy matter, and public records stay visible for years.
For e-resident founders, the smartest approach in 2026 is simple: prepare earlier than the deadline, clarify activity correctly, and avoid unnecessary pressure.
If you are unsure how your company should report this year, getting clarity early is always easier than correcting mistakes later.
Need help with your 2026 annual accounts?
Unicount supports e-resident founders with annual report preparation, whether your company was active or had no activity during the year.
You can explore our support articles or contact our team directly through your Unicount Dashboard or web chat.
Last verified: June 2026 by Unicount team
Sign up for newsletter
and get the latest Estonian news and Unicount tips right to your inbox